
CGT Reform 2027: What you need to know
From 1 July 2027, the proposed CGT changes will affect how gains are calculated on many assets, including investment properties, commercial property, farmland, shares and pre-CGT assets.
On 12 May 2026, the Federal Government handed down one of the most significant tax reform budgets in decades. The proposed reforms passed parliament and received Royal Assent on 26 June 2026. They are now law.
Here is what is changing, what it means for you, and the key steps you can take to navigate future CGT obligations.
What Is Changing From 1 July 2027?
Three significant reforms take effect on 1 July 2027:
- The 50% CGT discount is retired — Individuals, trusts, and partnerships will no longer be able to apply the 50% CGT discount for assets held longer than 12 months. In its place, cost base indexation will be introduced to account for inflation.
- A minimum 30% tax rate on capital gains — Regardless of your personal marginal tax rate, a minimum 30% will apply to capital gains. This will affect those who previously benefited from lower effective rates.
- The pre-CGT exemption is removed — Properties acquired before 20 September 1985 that were previously exempt from CGT will be brought into the CGT regime. The cost base will reset at market value on 1 July 2027, with all future gains taxed under the new rules.
What Happens to Assets You Already Own?
The proposed changes operate in two parts, resulting in two separate capital gains calculations for assets held prior to 1 July 2027.
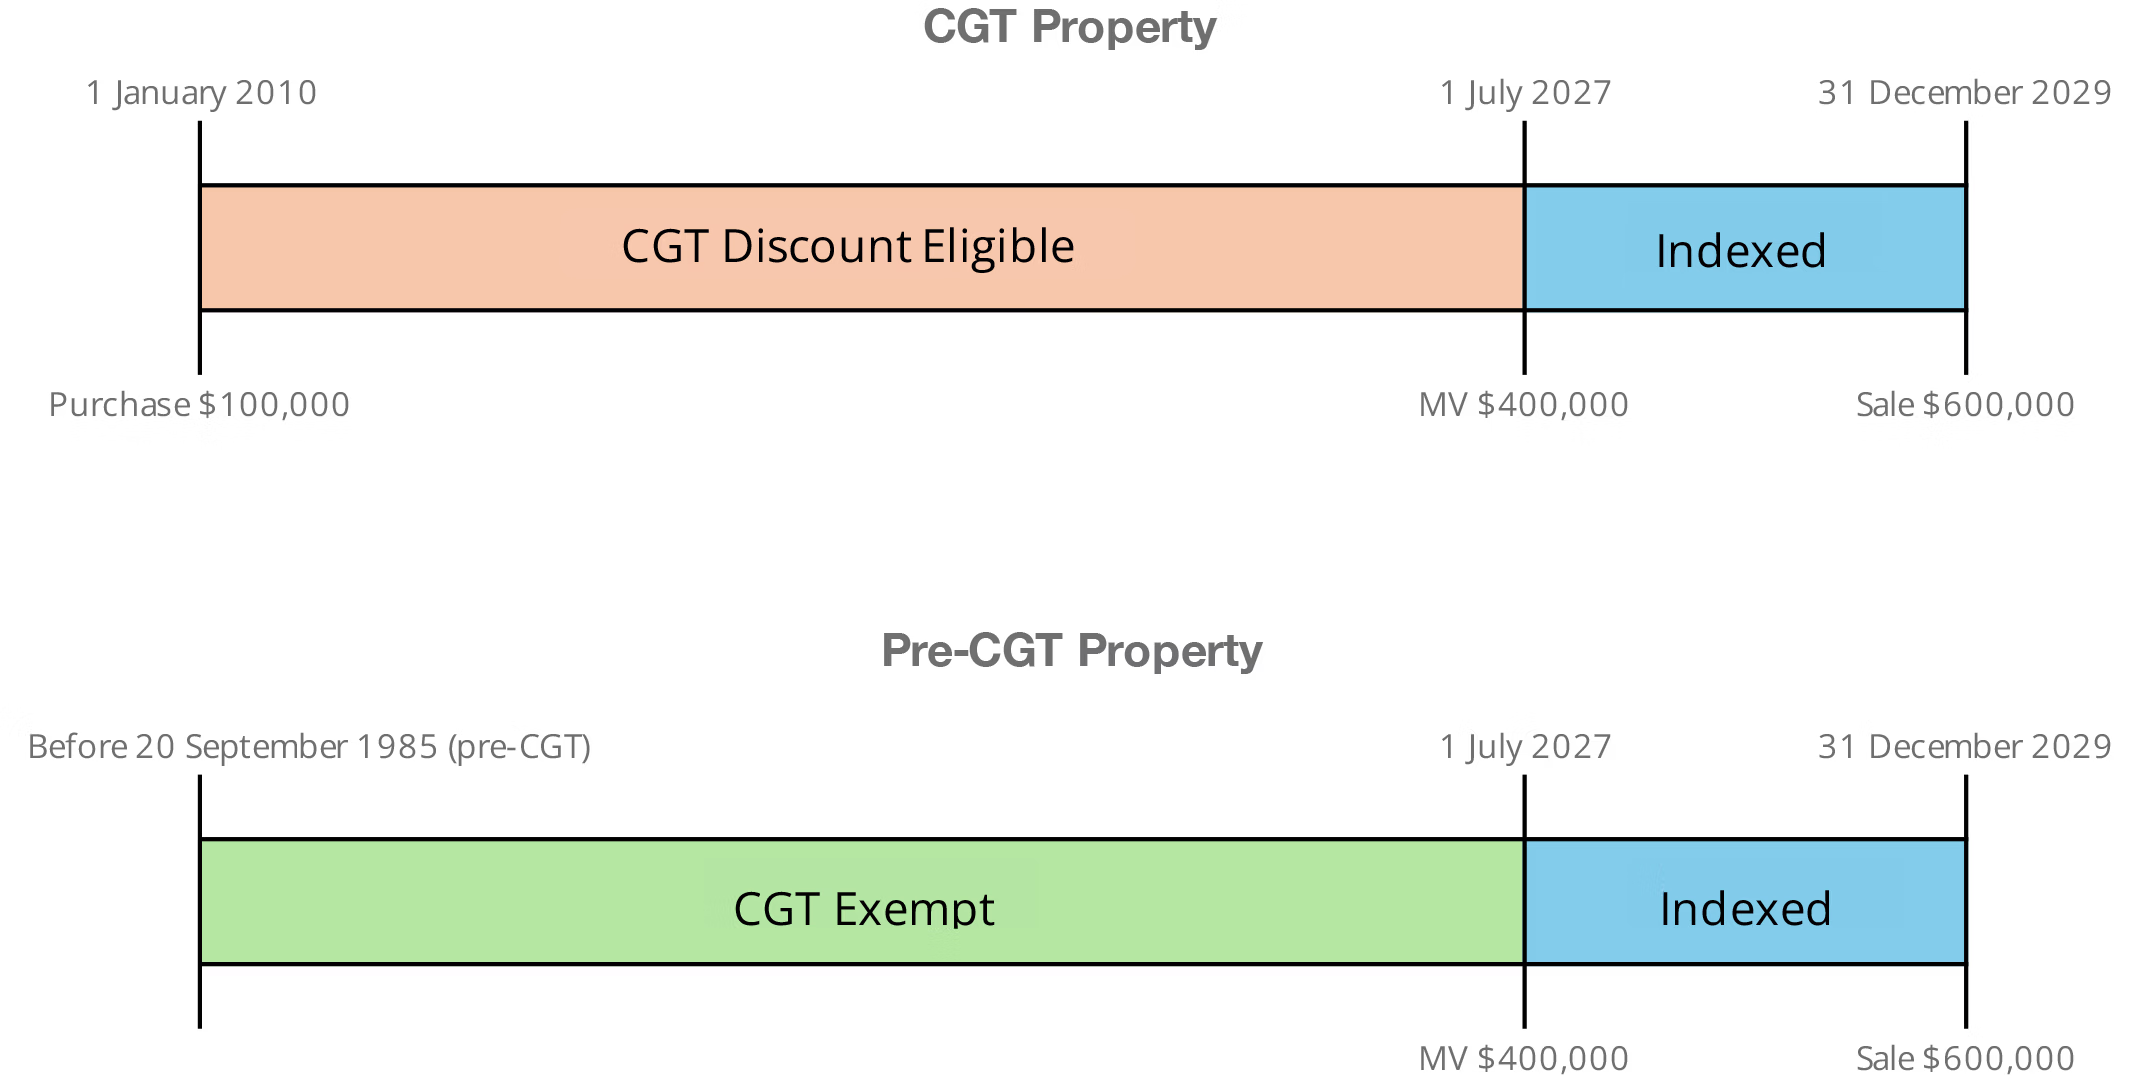
Calculation 1
Determine the net capital gain accrued up to 30 June 2027. For eligible assets and entities, the existing 50% CGT discount will continue to apply.
Calculation 2
Determine the net capital gain accrued from 1 July 2027 onwards, which will be calculated under the new indexation regime.
After applying any available capital losses, the combined capital gain will be subject to tax at 30%.
The market value of your property on 1 July 2027 becomes the dividing line between the old rules and the new.
Why Independent Valuations Matter More Than Ever
Under the new legislation, taxpayers have two options for determining their property's market value on 1 July 2027:
- An independent market rate valuation obtained from a qualified valuer; or
- An ATO-calculated metric — the ATO has proposed an apportionment formula.
An independent valuation provides a defensible market value supported by professional evidence. While both outcomes can be considered, reliance on a market value approach requires an independent valuation.
A higher, well-supported market value on 1 July 2027 works in your favour in several ways:
- More of your historical gain is eligible for the 50% discount.
- Less of your gain falls under the new higher-tax regime.
- You have documented evidence to withstand ATO scrutiny.
- Future planning — including succession and estate planning.
Waiting until the point of sale to obtain a valuation carries risk. Without a valuation as at 1 July 2027, substantiating the back dated value may prove difficult and any ATO action could be harder to defend.
Special Considerations for Pre-CGT Assets
If you own a property/asset acquired before 20 September 1985, this reform affects you directly. Properties that have historically been free from CGT will be brought into the CGT landscape for all future gains from 1 July 2027 onward.
For many Australian families, these are not just investment assets — they are generational properties, including long-held farmland that has been passed down through generations. The removal of the pre-CGT exemption is a significant event that may need to be factored into existing succession plans.
Key questions to consider for pre-CGT assets include:
- Which entity currently holds the asset — individual, company, family trust?
- Does the ownership structure support your current succession goals?
- Would restructuring into a family trust or land trust better protect the asset and align with your intentions?
- Is your existing succession plan still fit for purpose in the context of these changes?
The upcoming valuation date of 1 July 2027 creates a natural and timely checkpoint to review long-term ownership and succession strategies.
Be Proactive & Review Your Options
→ Seek advice on obtaining an independent valuation come 1 July 2027 to establish and support the property market value.
→ Review your property ownership structures — individual, company, or trust — to confirm they align with your goals.
→ Revisit your succession plans, particularly if you hold pre-CGT assets, as the proposed changes may influence future decisions.
→ Discuss your circumstances with your adviser to understand how the changes may affect your specific assets and plans.
Bottom Line
The proposed CGT changes from 1 July 2027 will impact many individuals who own assets, including residential investment properties, commercial properties, farming land, and shares. In some circumstances, shareholders in private companies may also need to obtain valuations to support future CGT calculations.
While these changes will alter the way capital gains are calculated and taxed, they do not remove the opportunity to plan ahead. With the right advice and timely action, there are still strategies available to help you manage the impact and make informed decisions for the future.
Speak to a Murray Nankivell adviser today

Related Insights

Murray Nankivell appoints two new Associate Directors
Murray Nankivell appoints two new Associate Directors
Murray Nankivell appoints Hamish Watson and William Altmann as Associate Directors, recognising their expertise and commitment to clients.
Tim Mason appointed Director of Murray Nankivell Financial Planning
Tim Mason appointed Director of Murray Nankivell Financial Planning
Tim Mason has been appointed Director of Murray Nankivell Financial Planning, recognising his experience, leadership and client focus.
Rates, Rain and Repayments
Rates, Rain and Repayments
Changing interest rates can pressure farm cash flow. Forecasting and scenario planning can help primary producers prepare and plan ahead.
We are here for you
We look forward to working with you to help you achieve a better financial future. Let us guide you on the path to financial success.
Contact your preferred Murray Nankivell office today.