
Lower tax instalments for small business – PAYG in 2022-23
PAYG instalments are regular prepayments made during the year of the tax on business and investment income. The actual amount owing is then reconciled at the end of the income year when the tax return is lodged.
Normally, GST and PAYG instalment amounts are adjusted using a GDP adjustment or uplift. For the 2022-23 income year, the Government has set this uplift factor at 2% instead of the 10% that would have applied. The 2% uplift rate will apply to small to medium enterprises eligible to use the relevant instalment methods for instalments for the 2022-23 income year:
- Up to $10 million annual aggregated turnover for GST instalments, and
- $50 million annual aggregated turnover for PAYG instalments
The effect of the change is that small businesses using this PAYG instalment method will have more cash during the year to utilise. However, the actual amount of tax owing on the tax return will not change, just the amount you need to contribute during the year.

Related Insights
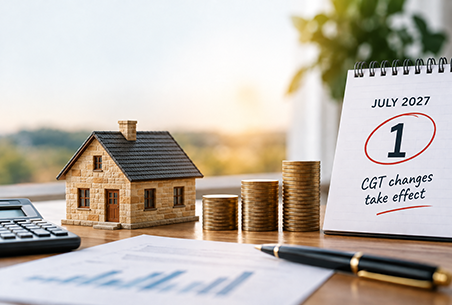
CGT Reform 2027: What you need to know
CGT Reform 2027: What you need to know
From 1 July 2027, CGT rules change for property and other assets. Learn what’s changing, why valuations matter and how to prepare.

Murray Nankivell appoints two new Associate Directors
Murray Nankivell appoints two new Associate Directors
Murray Nankivell appoints Hamish Watson and William Altmann as Associate Directors, recognising their expertise and commitment to clients.
Tim Mason appointed Director of Murray Nankivell Financial Planning
Tim Mason appointed Director of Murray Nankivell Financial Planning
Tim Mason has been appointed Director of Murray Nankivell Financial Planning, recognising his experience, leadership and client focus.
We are here for you
We look forward to working with you to help you achieve a better financial future. Let us guide you on the path to financial success.
Contact your preferred Murray Nankivell office today.